Documents Required for Home Loan
Applying for a home loan is easier when all the required documents are ready in advance. Banks and housing finance companies generally verify the applicant’s identity, income, employment/business, financial history, and property documents before approving a home loan.
The exact requirements can vary depending on the lender, whether you are salaried or self-employed, and the type of property you are purchasing.
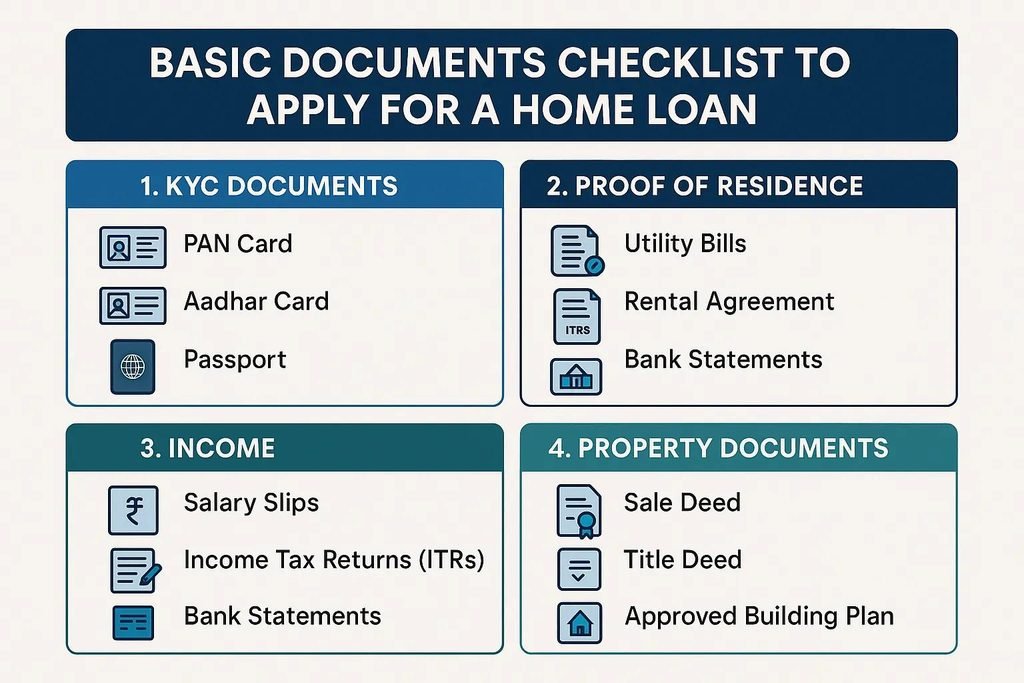
1. KYC & Identity Documents
- PAN Card
- Aadhaar Card
- Passport
- Voter ID
- Driving Licence
- Address proof, wherever required
- Recent passport-size photographs
2. Income Documents for Salaried Applicants
Typically, lenders may ask for:
- Latest 3–6 months’ salary slips
- Bank statements for the last 6 months
- Form 16 for the previous 1–2 financial years
- Income Tax Returns, if applicable
- Employment or appointment details, if required
3. Documents for Self-Employed Applicants
Self-employed applicants may need:
- ITRs for the previous 2–3 financial years
- Balance Sheet and Profit & Loss statements
- Business registration/proof
- GST returns, where applicable
- Current account/bank statements
- Business address proof
- Partnership deed or company documents, where applicable
4. Property Documents
These are particularly important because the lender conducts legal and technical verification of the property.
Depending on the property, documents may include:
- Agreement to Sale
- Sale Deed/Title Deed
- Previous chain of title documents
- Approved building plan
- Commencement Certificate, where applicable
- Occupancy Certificate (OC), where applicable
- Completion Certificate (CC), where applicable
- Property tax receipts
- Encumbrance-related documents, where applicable
- RERA registration details for applicable projects
- Allotment Letter for under-construction projects
- Builder-Buyer Agreement
- Possession Letter, where applicable
5. Additional Documents
Depending on your circumstances, the lender may also request:
- Existing loan statements
- Details of ongoing EMIs
- Proof of down payment
- Co-applicant documents
- NOC from the relevant authority, where applicable
- Additional financial statements or investment proofs
Why Property Documents Matter
Getting a home loan approved does not automatically mean that every aspect of the property’s title is risk-free. The bank performs its own legal and technical assessment, but buyers should also independently verify important property documents before purchasing.
For buyers in Ahmedabad and Gujarat, checking title, approvals, RERA details, development permissions and relevant municipal documents can be an important part of property due diligence.
Home Loan Document Checklist
| Category | Common Documents |
|---|---|
| Identity | PAN, Aadhaar, Passport/other ID |
| Address | Aadhaar, utility bill/other accepted proof |
| Salaried Income | Salary slips, Form 16, bank statements |
| Self-Employed Income | ITR, P&L, Balance Sheet, GST documents |
| Property | Sale Deed, Agreement to Sale, title documents |
| Approvals | Approved plan, OC/CC, applicable permissions |
| Project | RERA details, allotment letter, builder documents |
| Financial | Existing loan/EMI details, down-payment proof |
Final Checklist Before Applying
Before submitting your home loan application, keep KYC documents, income proof, bank statements and property papers organised. This can help reduce delays during loan processing and property verification.
Nine One Realty can also assist home buyers in Ahmedabad with property selection and document-oriented property due diligence.
Website: www.nineonerealty.com
Phone: +91 99740 00200